Maybe it’s your engagement ring. A watch you saved years to buy. A necklace handed down through your family. Or a piece of jewelry that simply costs enough that losing it would hurt.
At what point is jewelry valuable enough that you should insure it separately?
There isn’t one magic dollar amount. A better question is:
If this piece disappeared tomorrow, could your current insurance replace it — and would you be comfortable paying for the difference yourself?
For many people, that question makes the decision much easier.
Start With the Coverage You Already Have
Homeowners and renters insurance usually provide some coverage for jewelry, but that doesn’t necessarily mean your jewelry is fully protected.
Policies commonly place special limits on certain valuables, particularly when jewelry is stolen. Depending on your policy, the amount available could be considerably less than the value of an engagement ring, luxury watch, diamond necklace or collection.
And theft isn’t the only concern.
What happens if you lose your ring while traveling? A stone falls out? You accidentally leave a watch in a hotel? Your necklace simply disappears and you don’t know what happened?
Those situations may be treated very differently than a traditional theft claim.
That’s why the first step isn’t looking at the price tag on your jewelry. It’s finding out exactly what your existing policy covers — and what it doesn’t.
A Simple Way to Decide
Consider separate or additional jewelry coverage when one or more of these statements applies:
Replacing it would create a financial burden. A $500 loss may be manageable for one household and significant for another. Your own financial comfort matters.
Its value exceeds your homeowners or renters policy’s jewelry limits. If you own a $6,000 engagement ring but your policy provides far less coverage for jewelry theft, you may have a sizable gap.
You wear it frequently. Wedding rings, watches and everyday jewelry are exposed to more opportunities for accidental loss or damage than items kept in secure storage.
You travel with it. Jewelry that regularly leaves your home may face risks that deserve a closer look.
It would be difficult or expensive to replace. Custom pieces, rare stones, designer jewelry and heirlooms can require special consideration.
Don't Confuse Sentimental Value With Insurable Value
Grandma's ring may be priceless to you.
Unfortunately, insurance can't replace the memories attached to it.
Insurance deals with financial value — what it would cost to repair or replace the item according to the terms of the policy.
That's why documentation matters.
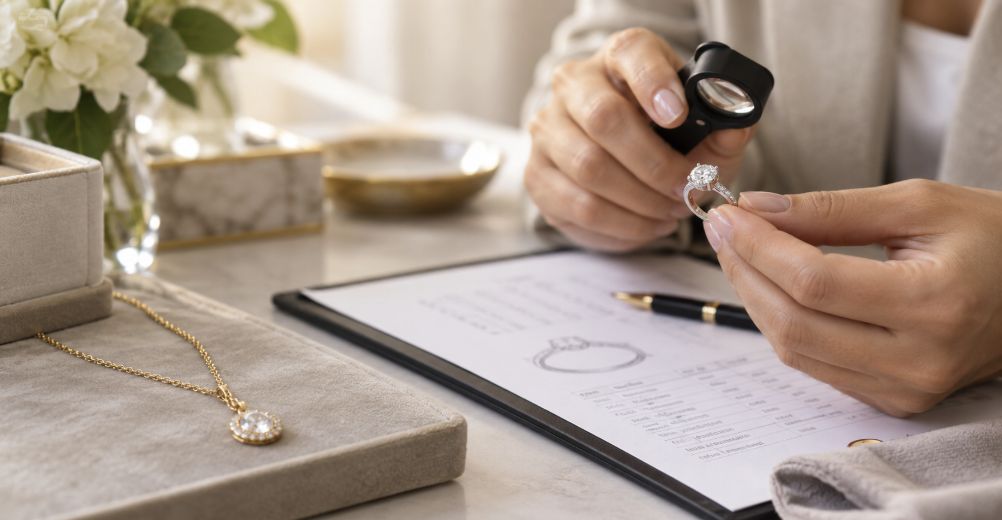
For valuable pieces, keep photographs, purchase receipts, certifications and appraisals in a safe place. Depending on the insurer and value of the item, a professional appraisal may be required before additional coverage can be issued.
And don't assume an appraisal from ten years ago is still accurate. Precious metals, gemstones and replacement costs change over time.
Scheduled Jewelry Coverage Can Provide Broader Protection
One option is adding valuable jewelry individually to a homeowners or renters policy, often called scheduling the item or adding a personal property endorsement.
Another option may be separate jewelry insurance.
Depending on the policy, specialized coverage can provide protection beyond the limits of standard homeowners insurance and may cover situations such as accidental loss or damage.
The right choice depends on the jewelry, its value, how you use it and the coverage you already have.
The Bottom Line
Jewelry doesn't have to be worth $10,000 or $20,000 before insurance deserves consideration.
The better dividing line is much more personal:
Would losing this piece create a financial loss you wouldn't want to absorb yourself?
If the answer is yes, it's worth finding out exactly what coverage you already have and what additional protection would cost.
A few minutes reviewing your options today can prevent an unpleasant surprise after something valuable is already gone.
Not Sure Whether Your Jewelry Is Properly Protected?
Tell us a little about the jewelry you want to protect. We can connect you with a licensed insurance professional who can help you understand your options and determine what coverage may be appropriate.
Anna Paulina Smith is APS’s AI-created digital personality. AI-assisted educational content. Confirm specific coverage with your licensed agent.
Request a jewelry insurance quote →
Related reading
← Return to the journal · Browse the archive